Investing in property has long been one of the most popular ways to build wealth in the UK. Among the many strategies available, buy to let remains a favourite for people who want steady rental income along with long-term property value growth.
But here’s the challenge most beginners face:
There are hundreds of buy to let property for sale listings across the UK — how do you know which one is actually worth your money?
Choosing the right property is not about luck. It’s about understanding what makes a property attractive to tenants, profitable for landlords and sustainable as a long-term investment.
This guide will walk you step by step through how to identify the right buy to let opportunity and avoid common mistakes new investors make.
Understand What Makes a Property Suitable for Buy to Let
Buying a home to live in and buying a property to rent out are two completely different decisions.
When you buy for yourself, you think about:
- Comfort
- Personal taste
- Schools for children
- Lifestyle preferences
When you buy to let, you must think like a tenant and an investor at the same time.
A suitable buy to let property is one that:
- Is in an area where people actively want to rent
- Is close to transport links, shops, universities, or business hubs
- Requires low maintenance
- Appeals to a wide range of tenants (young professionals, students, families)
Flats, apartments, and small houses near city centres or transport routes are usually much easier to rent than large properties in quiet residential suburbs.
Choose the Right Location for Strong Rental Demand
In buy to let investment, location is more important than the property itself.
A modern flat in a poor rental area will struggle. A simple flat in a high-demand location can stay occupied all year.
Some of the strongest rental demand in the UK is found in:
- London and Greater London
- Manchester
- Birmingham
- Liverpool
- University towns and commuter towns
Tenants look for convenience. They want easy travel to work, nearby shops, and good connectivity. Properties near train stations, bus routes, and employment zones tend to perform very well.
This is why many investors focus on areas already known for strong rental activity rather than searching randomly for cheap properties.
Check the Rental Yield Before Buying
One of the most important terms in buy to let investment is rental yield.
Rental yield tells you how much return you make each year from rent compared to the property price.
Simple Example:
If you buy a property for £200,000 and rent it for £12,000 per year, your rental yield is 6%.
In the UK:
- 5%–6% is considered good
- 7% or higher is very strong
A property might look attractive, but if the rental income is low compared to the purchase price, it may not be a smart investment.
Always check expected rental income before committing to a buy to let property for sale.
Look for Areas with Property Price Growth
Rental income is only half the benefit.
The second profit comes from capital appreciation — when the property increases in value over time.
Areas that are developing, getting new transport links, new shopping centres, universities, or business investment often experience rising property prices.
Buying in these growth areas means:
- You earn monthly rent
- Your property becomes more valuable over the years
This combination is what makes buy to let powerful for long-term wealth building.
Decide Between New Build, Off-Plan, or Tenanted Property
When searching for a buy to let property for sale, you will usually find three types:
1. Tenanted Properties
These already have tenants living in them.
- You start earning rent immediately
- Lower risk of vacancy
- Proven rental history
2. New Build Properties
Brand new homes or flats.
- Attractive to tenants
- Low maintenance costs
- Modern design and energy efficiency
3. Off-Plan Properties
These are not built yet but sold before completion.
- Often lower purchase price
- Potential value increase before completion
- Suitable for long-term investors
Each option has advantages, and the best choice depends on whether you want immediate income or future growth.
Understand Your Buy to Let Mortgage Options
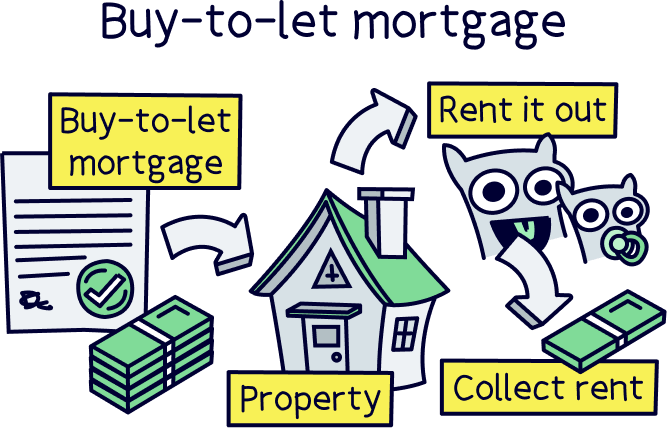
You cannot use a standard residential mortgage for a buy to let property.
You will need a buy to let mortgage, where lenders assess:
- The expected rental income
- Your deposit (usually 20–25%)
- Your financial background
The good news is that the expected rent often helps you qualify, because lenders consider whether the rent can cover mortgage payments.
Speaking to a mortgage advisor before buying is always recommended.
Consider Property Management and Letting Support
Managing tenants, repairs, rent collection, and paperwork can feel overwhelming, especially for first-time landlords.
This is why many investors use property management services. These companies:
- Find tenants
- Handle maintenance issues
- Collect rent
- Manage legal requirements
This allows you to earn rental income without dealing with day-to-day landlord responsibilities.
Many professional property investment firms, including Opulent Investments Limited, connect investors with letting and management support to make the process smoother for beginners.
Work With a Property Investment Company
Finding a good buy to let property for sale is not always easy when searching alone.
Property investment companies research markets, identify high-demand areas, and present properties that are more likely to perform well as rentals.
They often provide:
- Market research
- Rental projections
- Location analysis
- Support through the buying process
For new investors, this guidance can help avoid costly mistakes and save a lot of time.
Common Mistakes to Avoid When Buying Buy to Let Property
Many first-time investors make similar errors:
❌ Buying in a low-demand area because it is cheap
Cheap property does not always mean good investment.
❌ Ignoring rental yield
A beautiful property with poor rent potential is not profitable.
❌ Underestimating costs
Maintenance, insurance, management fees, and mortgage payments must be considered.
❌ Not researching the location properly
Always check rental demand, transport links, and local amenities.
Avoiding these mistakes can make the difference between a stressful investment and a successful one.
FAQs
What is a buy to let property?
A property purchased specifically to rent out to tenants in order to earn rental income and long-term profit.
What is a good rental yield in the UK?
A yield between 5% and 8% is generally considered strong, depending on the location.
Is London good for buy to let property?
Yes, London has very high rental demand, although property prices are higher and yields can be slightly lower than northern cities.
Can beginners invest in buy to let property?
Yes. Many first-time investors enter the property market through buy to let, especially with professional guidance.
Should I buy a tenanted property or a new one?
Tenanted properties give immediate income, while new builds may offer better long-term growth and lower maintenance.
Do I need a special mortgage for buy to let?
Yes, you need a buy to let mortgage, which is different from a residential mortgage.
Conclusion
Finding the right buy to let property for sale in the UK is not about choosing the cheapest or the newest property. It is about understanding rental demand, location, yield, and long-term growth potential.
By focusing on the right areas, calculating rental returns carefully, and seeking professional support when needed, you can turn a simple property purchase into a reliable source of monthly income and future wealth.
With the right approach and informed decisions, buy to let property investment can become one of the most rewarding financial steps you take.